Introduction
Getting into cryptocurrency feels exciting. You set up a digital wallet, buy your first coins on an exchange, and watch the market move up and down. But sooner or later, every crypto investor faces a confusing reality: taxes.
Many beginners assume crypto exists outside the traditional financial system, meaning tax rules do not apply until you cash out to your bank account. Unfortunately, tax authorities view things differently. misunderstanding how crypto is taxed can lead to surprise tax bills, penalties, or audits.
This guide breaks down cryptocurrency taxation in simple English. You will learn how different crypto activities are taxed, the difference between capital gains and income, common mistakes to avoid, and how to keep clean records.
What Is Cryptocurrency Taxation?
Cryptocurrency taxation refers to the rules and laws applied by governments to digital assets. Because tax agencies do not classify crypto as official legal tender (like paper cash), they treat it as property.
Think of crypto like owning shares of stock, digital gold, or real estate. When you buy a house and its value goes up, you do not owe tax just for owning it. But the moment you sell that house, trade it for another property, or use it to buy a car, you must calculate your profit or loss and report it to the government. Crypto works the exact same way.
Why It Matters
Tax authorities track digital asset transactions using advanced blockchain analytics and reporting requirements from major cryptocurrency exchanges. Ignoring crypto taxes is risky. Knowing the rules helps you keep more of your hard-earned money legally while staying compliant with the law.
How Crypto Taxes Work: The Core Concepts
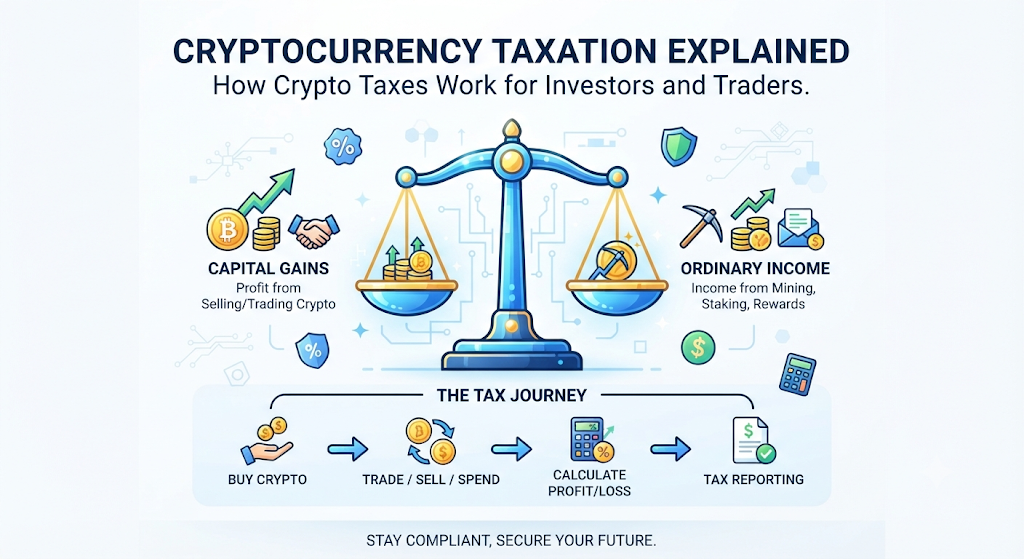
To understand crypto taxes, you need to understand two main buckets: Capital Gains and Ordinary Income.
1. Capital Gains (Buying, Selling, and Trading)
A capital gain happens when you dispose of a capital asset (like crypto) for more than what you paid for it. A capital loss happens if you sell it for less.
- Capital Asset: Any cryptocurrency you own for investment or personal use.
- Disposal: Selling crypto for cash, trading one crypto for another (e.g., swapping Bitcoin for Ethereum), or buying goods and services with crypto.
Capital gains are split into two categories based on how long you held the asset before selling:
- Short-Term Capital Gains: If you held the crypto for one year or less, your profit is taxed at your ordinary income tax rate.
- Long-Term Capital Gains: If you held the crypto for more than one year, your profit is taxed at lower preferential rates (usually 0%, 15%, or 20% depending on your income bracket).
2. Ordinary Income (Mining, Staking, and Rewards)
When you earn new cryptocurrency through work or network participation, tax agencies view it as receiving a paycheck or business income.
- Mining: Solving complex mathematical equations to secure a proof-of-work blockchain and earning newly minted coins.
- Staking: Locking up your crypto to help validate transactions on a proof-of-stake network and earning rewards.
- Airdrops and Hard Forks: Receiving free tokens distributed by a project or created through a blockchain split.
This income is taxed based on the fair market value of the cryptocurrency on the exact day and time you received it. If you later sell that earned crypto, you will also owe capital gains tax on any price increase from the day you received it.
Common Crypto Activities and Their Tax Treatment
Let us look at how everyday crypto actions trigger tax responsibilities.
| Crypto Activity | Tax Classification | When Tax Is Triggered |
|---|---|---|
| Buying crypto with fiat (USD/EUR) | Not taxable | When you buy and hold |
| Selling crypto for fiat | Capital Gain / Loss | At the moment of sale |
| Trading Crypto A for Crypto B | Capital Gain / Loss | At the moment of the trade |
| Buying a coffee with Bitcoin | Capital Gain / Loss | At the moment of purchase |
| Receiving mining/staking rewards | Ordinary Income | When the rewards hit your wallet |
| Receiving a crypto paycheck | Ordinary Income | When you receive the funds |
| Transferring crypto between your own wallets | Not taxable | Never (no ownership change) |
| Gifting crypto | Usually non-taxable to giver | When recipient sells |
The Crypto-to-Crypto Trap
Many beginners make the mistake of thinking taxes only apply when converting crypto back into government-issued cash (fiat).
Example: You buy $500 worth of Bitcoin. A year later, that Bitcoin grows in value to $1,200. You use that Bitcoin to buy an altcoin on a decentralized exchange.The Reality: The IRS and other tax agencies treat that crypto-to-crypto trade as a simultaneous sale of Bitcoin and purchase of an altcoin. You must report a capital gain on the $700 profit, even though you never touched US dollars.
Practical Examples to Clear the Confusion
Example 1: Short-Term Trading
Sarah buys 1 Ethereum for $2,000 in January. In June, the price jumps to $3,500, and she sells it for cash.
- The Result: Sarah made a short-term capital gain of $1,500 ($3,500 minus her $2,000 cost basis). Because she held it for less than a year, this $1,500 is added to her regular yearly job income and taxed at her standard income tax bracket.
Example 2: Staking Rewards
Mark stakes his Solana tokens and receives $300 worth of Solana tokens over the course of the year as staking rewards.
- The Result: When Mark receives those rewards, he must report $300 of ordinary income on his tax return based on the market value at the time they dropped into his wallet. Later, if he sells those tokens for $450, he owes capital gains tax on the $150 price increase.
Real-World Considerations and Record Keeping
Tracking your crypto transactions manually can quickly become a nightmare, especially if you use multiple exchanges, decentralized finance (DeFi) platforms, and hardware wallets.
Cost Basis Methods
Your cost basis is what you originally paid for your crypto, including any transaction or exchange fees. When you sell part of your holdings, you need a method to calculate which coins you are selling:
- FIFO (First-In, First-Out): The oldest coins you bought are assumed to be the first ones you sold.
- LIFO (Last-In, First-Out): The newest coins you bought are assumed to be sold first.
- Specific Identification: You explicitly choose which specific units you are selling by matching purchase dates and prices.
Crypto Tax Software
Because blockchains process thousands of transactions across different networks, most active investors use specialized crypto tax software (such as CoinLedger, Koinly, or TaxBit). These tools connect to your wallet addresses and exchange APIs via read-only keys to automatically calculate your gains, losses, and income.
Common Mistakes Beginners Make
- Assuming small trades do not count: Tax agencies require reporting all capital gains, regardless of how small the transaction amount is.
- Failing to track wallet-to-wallet transfers: Moving funds from Coinbase to a Ledger hardware wallet is not a taxable event, but failing to log it can make tax software think you sold your coins.
- Ignoring airdrops and forks: Free tokens given to your wallet are considered taxable income the moment you gain control over them.
- Waiting until tax season to organize data: Trying to piece together three years of wallet history in April leads to errors, missed losses, and overpaid taxes.
Risks and Limitations
- Regulatory Changes: Tax laws surrounding digital assets are evolving rapidly. Countries frequently update guidance on NFTs, staking, and decentralized finance (DeFi).
- Loss of Records: If an exchange goes bankrupt or shuts down and you lose your transaction history, reconstructing your cost basis legally becomes extremely difficult.
- Wash Sale Rules: In traditional stock markets, selling an asset at a loss and buying it back immediately is restricted by wash sale rules. While traditional crypto wash sale rules vary by jurisdiction, tax authorities are closing loopholes around artificial loss harvesting.
Checklist: Preparing Your Crypto Taxes
- Gather all accounts: List every centralized exchange (Binance, Coinbase, Kraken), decentralized wallet (MetaMask, Phantom), and hardware wallet (Ledger, Trezor) you used during the tax year.
- Export transaction histories: Download CSV files or connect API keys for every platform.
- Account for transfers: Ensure wallet-to-wallet transfers are labeled correctly as transfers, not sales or income.
- Calculate gains, losses, and income: Use reputable crypto tax calculation software or work with a certified public accountant (CPA) who specializes in digital assets.
- File your return: Report your capital gains and ordinary income on the appropriate tax forms required by your local tax authority.
Key Terms
- Cost Basis: The original purchase price of an asset, including fees, used to calculate capital gains or losses.
- Capital Gain: The profit you make when you sell or dispose of an asset for more than your cost basis.
- Capital Loss: The financial loss incurred when you sell an asset for less than your cost basis.
- Fiat Currency: Government-issued money that is not backed by a physical commodity, like US Dollars or Euros.
- Fair Market Value: The estimated price an asset would sell for on the open market at a specific time.
- Staking: The process of locking up cryptocurrency tokens to support network security in exchange for reward payouts.
- Mining: Validating transactions on a proof-of-work blockchain using computing power to earn new coin rewards.
- Wallet Address: A alphanumeric string used to send and receive digital assets on a blockchain.
Frequently Asked Questions
Do I have to pay taxes if I only bought crypto with dollars and kept it in my wallet?
No. Simply buying cryptocurrency with fiat currency and holding it in your private wallet or exchange account is not a taxable event. You only trigger taxes when you dispose of (sell, trade, or spend) the asset.
Does transferring crypto from Binance to MetaMask trigger taxes?
No. Transferring digital assets between wallets or accounts that you own is a non-taxable event because you still retain ownership of the asset.
How are NFT purchases and sales taxed?
NFTs (Non-Fungible Tokens) are treated similarly to cryptocurrencies. Buying an NFT with cryptocurrency is considered a disposal of that crypto, triggering a capital gain or loss. Selling an NFT for profit also triggers a capital gains tax.
Can I use crypto losses to lower my taxes?
Yes. If your capital losses exceed your capital gains in a given year, you can use those losses to offset other taxable income (up to certain limits, such as $3,000 per year in the US), or carry them forward to future tax years.
What happens if I forget to report my crypto transactions?
Failing to report crypto taxes can result in automated notices from tax agencies, heavy financial penalties, interest charges, and in severe cases of tax evasion, legal prosecution.
Are airdrops taxable when I receive them?
Yes. Tax authorities generally view airdrops and hard forks as ordinary income. You must report the fair market value of the tokens on the day you gain dominion and control over them.
Do I need a CPA to file crypto taxes?
While simple buy-and-hold investors can often use crypto tax software independently, individuals who engage in complex DeFi transactions, margin trading, high-frequency trading, or NFT minting often benefit greatly from hiring a CPA who understands digital asset taxation.
Conclusion
Cryptocurrency taxation can seem intimidating at first, but the foundational rules come down to treating digital assets as property. Keeping clear records of your trades, understanding the difference between capital gains and income, and using automated tracking tools can save you time, money, and stress. Stay organized throughout the year, and approach your crypto taxes with the same care you apply to traditional investments.